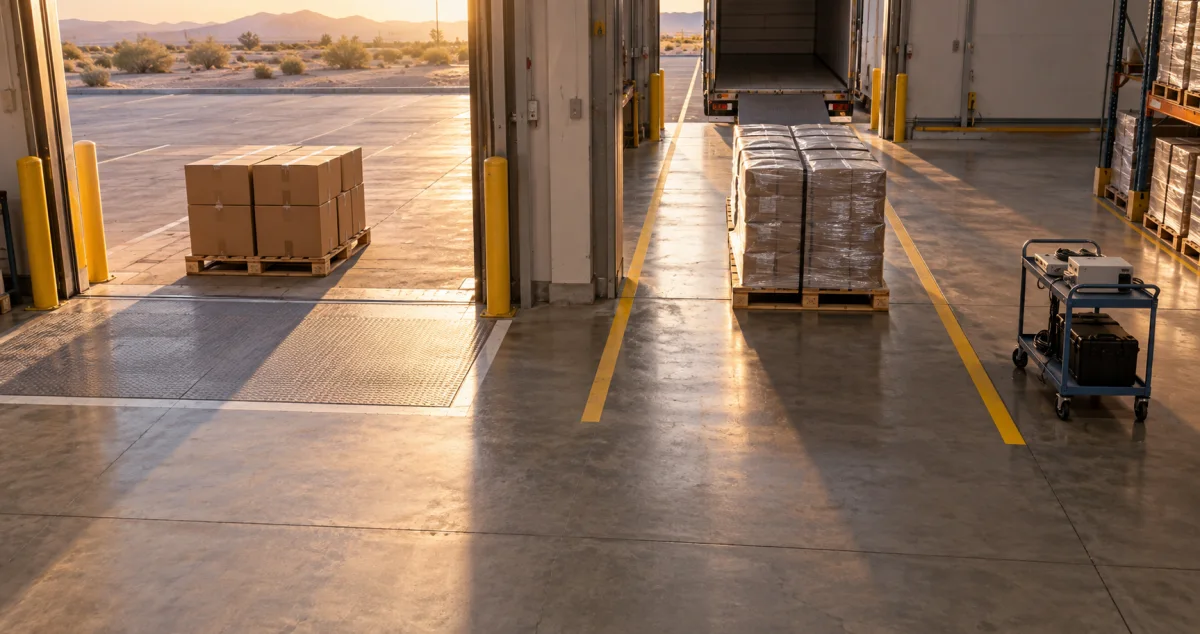
A truck waits to unload outside the warehouse. Customer orders sit in dispatch awaiting collection, while a side shelf holds customer-owned appliances received for repair. Starting the count with only “how many pieces are here?” confuses physical presence, the ownership or control relevant to accounting, and the period to which movements belong.
Preparing for the 2024 inventory close does not require assuming year-end market results. It requires defining the measurement point and what belongs within it, then valuing quantities appropriately. The following examples are illustrative, not events at a named business or reported results for 2024.
The time at which the comparison stops
Define the count time, the system-balance extraction time and how movements between them will be controlled. If dispatch and receiving continue during counting, each movement needs a reference, time and clear location so goods are not counted twice or omitted from both places. Temporarily stopping movement can simplify the task, but where that is impractical the alternative needs organisation rather than guesswork.
Suppose 240 units of one item are counted at eight in the evening. Another 30 are received and 20 issued before period-end, with no other movements. If those transactions are established as belonging to the entity and period, the expected closing quantity is 250. Do not compare the original 240 with a system balance extracted after both movements and classify the ten-unit difference as a count variance.
Keep original count records, recount results and reasons for amendments. A recount is not an invitation to copy the system quantity onto the sheet until discrepancies disappear. Where scanning devices are used, check that codes and packaging units do not turn a carton into a single piece or vice versa.
Beyond the warehouse boundary
Goods in transit require examination of the contract, delivery terms and documents to establish treatment and period. Neither invoice date nor arrival date alone is sufficient. Branch transfers may have left the source without reaching the destination. At the same-entity level, quantities should neither vanish between locations nor appear in both.
Separate customer or supplier goods held on their behalf from the entity's own inventory in count records and reporting. Their presence establishes custody, not necessarily an asset belonging to the business. Conversely, obtain appropriate evidence of quantity and condition for the business's inventory held elsewhere instead of excluding it because it is absent from the warehouse walk-through.
Purchasing, sales and logistics must contribute to this review. An accountant cannot infer every shipment's terms from a quantity listing. Present unresolved items with their evidence rather than including or excluding them merely to obtain a comfortable total.
The quantity is right, but valuation asks another question
IAS 2 measures inventory at the lower of cost and net realisable value, with the latter reflecting expected selling price less necessary completion and selling costs. Successful counting is therefore not the end of the close. Examine damaged, slow-moving or commercially impaired items using relevant evidence rather than applying an unsupported blanket percentage.
Assume 50 units cost SAR 100 each. Supported estimates indicate a selling price of SAR 85 and necessary selling costs of SAR 5 per unit, with no completion costs. Net realisable value is SAR 80 per unit, giving a value of SAR 4,000 rather than cost of SAR 5,000: a SAR 1,000 write-down. Do not remove the fifty units from quantity records because their value has fallen. Quantity and valuation are separate dimensions.
Review the estimation basis, its date and the circumstances it describes. An exceptional offer does not necessarily represent what can be realised for the entire balance, while a high advertised price does not establish that a buyer exists. The conclusion needs evidence and an appropriate accounting decision, not a preference for higher or lower profit.
What carries into the next year?
Hand over detailed balances linked to the general ledger, together with count results, movement reconciliations, approved valuations and unresolved matters. Establish that opening balances use the same final version rather than an earlier extraction. A difference between closing and opening figures should not be hidden by a silent balancing entry.
Keep follow-up work explicit: a shipment awaiting evidence, a variance needing investigation or a cost estimate awaiting an invoice. Year-end does not erase those tasks, but their implications need appropriate assessment. A sound close leaves the next period with explainable figures, not carefully counted boxes whose connection to the records has been lost.
Sources & further reading
Visit the original source to explore the concept and its wider context.
General educational content. Appropriate treatment depends on your business and accounting policies; consult your accounting professional when applying it to business records.


